Find your exact debt-free date in 10 minutes.
Every card, loan, EMI and pay-later app on one screen. The right order to pay them off. And a date you can finally circle on the calendar.
Get my debt-free date for ₹599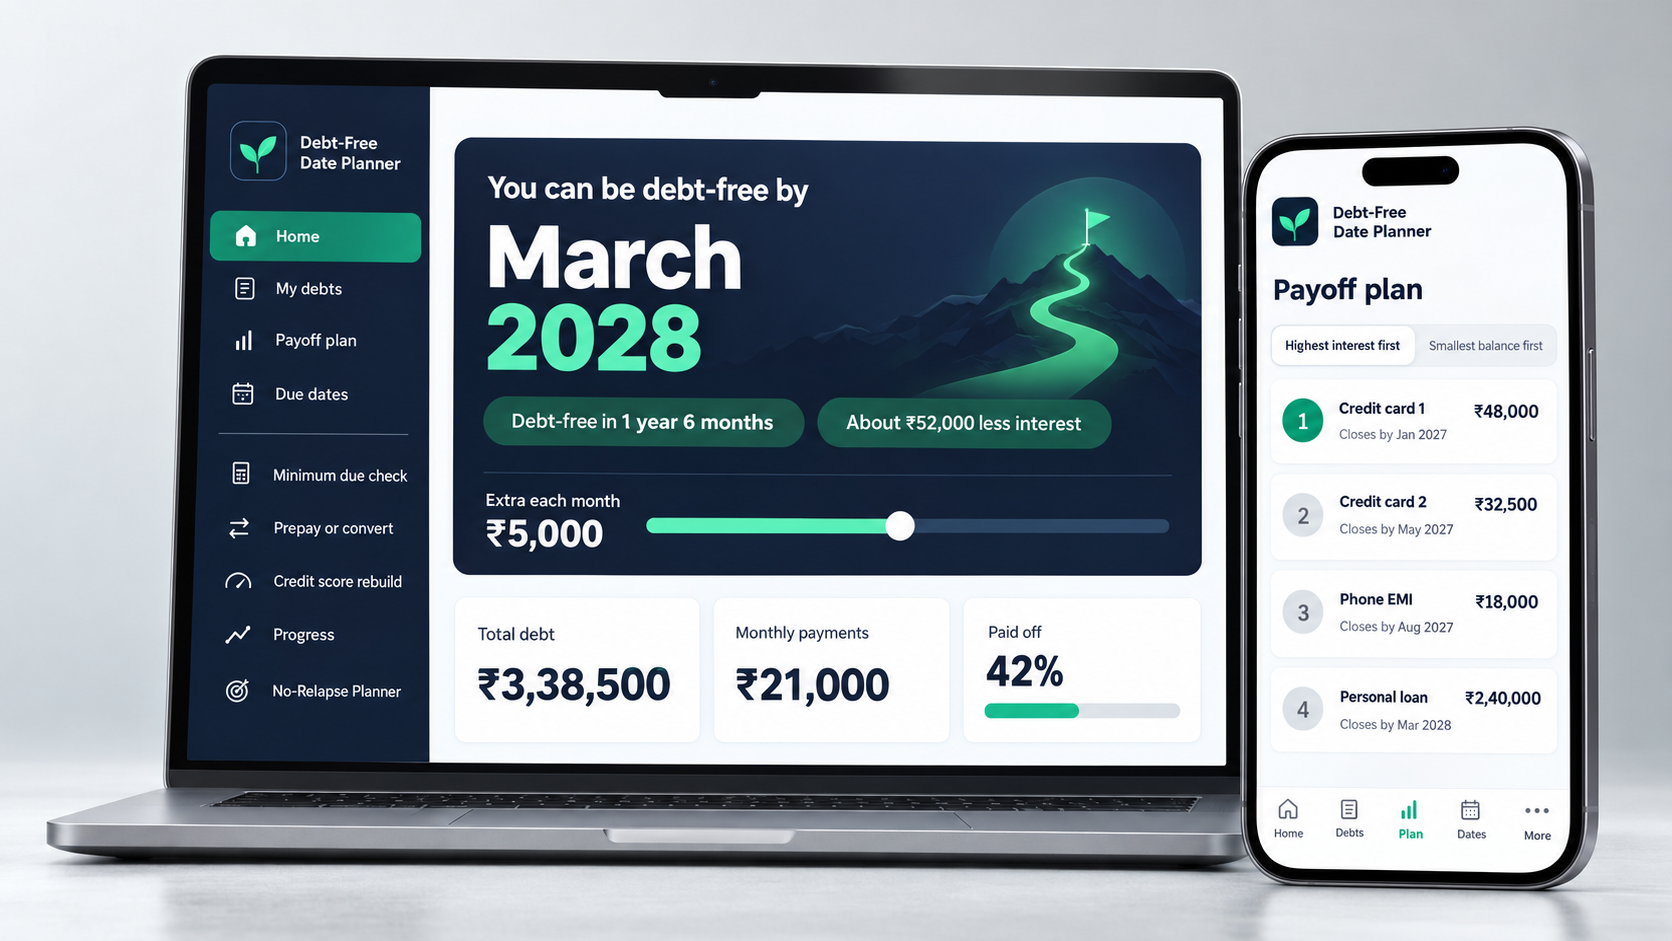
You earn well. So why does the money disappear by the 7th?
Two cards, a personal loan, a phone EMI, a pay-later app. Different due dates, different rates, different apps. And no idea when it ends.
I don't even know my total. I'm scared to add it up.
I earn ₹80k and still wait for the 1st like a college student.
I've paid for 2 years and the card still shows almost the same amount.
Every time an unknown number calls, my heart drops.
I just want to know when this will end. Even if it's 3 years, just tell me.
Paying the minimum feels safe. It's the most expensive choice you can make.
Take one ₹50,000 credit card balance at 42% a year, a common card rate. Here's the difference between paying the minimum due and paying a fixed amount.
Example calculated with the planner's own Minimum due check: minimum due of 5% of the balance, no new spending on the card. Real costs are usually higher because banks add GST on interest.
You don't need more willpower. You need an order.
Most people pay a little extra on everything, so nothing ever closes. The planner does the maths and shows you the one debt to attack first.
Map it
Every debt on one screen. Your real total, your monthly payments, and the interest you pay this month.
Target it
Pay minimums on everything else. Every extra rupee goes to one target: highest interest first, or smallest balance first. You choose.
Roll it
When a debt closes, its payment rolls into the next target. Each closed debt makes the next one faster.
A private app that does the maths for you
Works on your phone and laptop. Add it to your home screen and it opens like an app, even offline.
Your debt-free date
A real month and year, calculated from your own numbers. Drag the "extra per month" slider and watch it move closer.
Your payoff order
Highest interest first vs smallest balance first, side by side, with the month each debt closes.
Due dates and phone reminders
Every due date on one calendar, with reminders on your phone 2 days before. No more late fees.
Minimum due check
Enter any card and see how many years the minimum really takes, and what a fixed amount saves.
Progress you can see
A paid-off bar, a celebration each time a debt closes, a monthly log, and a printable PDF of your plan.
Built for Indian debt
Credit cards, personal loans, gold loans, phone EMIs, pay-later and app loans. All in rupees.
Your numbers never leave your phone
No signup, no bank login, no uploads. Everything you enter stays on your own device. Not even we can see it.
Plus 3 bonuses
Prepay or Convert Calculator
Should you prepay a loan or convert a card balance to EMI? See the exact interest and fees before you call the bank.
Credit Score Rebuild Checklist
15 steps to check your report, fix errors, and rebuild your score while you pay off debt. Built into the app.
Money Talk Kit
How to tell your spouse or parents about your debt, without the fight. Scripts, worksheets and a monthly check-in. In English and Hinglish.
One price. Yours to keep.
- One-screen debt map₹799
- Debt-free date engine with slider₹999
- Smart payoff order₹799
- Minimum due check₹299
- Due-date calendar and phone reminders₹399
- Progress tracker and printable plan₹399
- Bonus: Prepay or Convert Calculator₹499
- Bonus: Credit Score Rebuild Checklist₹299
- Bonus: Money Talk Kit (English and Hinglish)₹299
guarantee
The 10-Minute Clarity Guarantee
Enter your debts within 7 days of buying. If you don't see your total debt, payoff order and debt-free date clearly on one screen, message us. We'll help you set it up, or if you'd rather, we'll refund you in full. Email [email protected] or WhatsApp +91 98002 22991 with your order ID. No forms, no hard feelings.
Built for one kind of person
It's for you if
- You have 2 or more cards, loans, EMIs or pay-later accounts
- You earn a regular salary but feel broke every month
- You pay the minimum and the balance barely moves
- You want a clear plan, not a lecture
It's not for you if
- You're looking for a new loan or a debt settlement service
- You want someone else to negotiate with your bank for you
- You expect your debt to vanish without paying it
Before you buy
Is this an app I download from the Play Store?
No download needed. It's a web app that opens in your browser on any phone or laptop. Add it to your home screen and it opens like a regular app, even without internet.
Do I need to share my bank login or card details?
Never. You type in your own balances, rates and EMIs. Everything stays on your device. There's no signup and nothing is uploaded, not even to us.
What happens right after I pay?
You get an access PDF by email with your app link and personal access code. Open the link, enter the code, and start adding your debts. It takes about 10 minutes.
Is this a subscription?
No. You pay ₹599 once and it's yours.
Does it work with 0% EMIs, pay-later apps and app loans?
Yes. Credit cards, personal loans, gold loans, vehicle loans, phone EMIs, pay-later accounts and instant app loans all work. Even money you owe family can go in at 0%.
Can I use it on my phone and my laptop?
Yes. Your data lives on each device separately, for privacy. To move your numbers to another device, download a backup and restore it there. It takes one tap each way.
Is this financial advice?
No. The planner does the maths on the numbers you enter and shows your options clearly. The decisions stay yours.
What if it doesn't work for me?
Message us within 7 days with your order ID. We'll help you set it up, or refund you in full if you prefer.
Ten minutes from now, you could know your date.
Or you could spend another month paying the minimum, wondering when it ends. The planner costs less than most late fees.
Get my debt-free date for ₹599P.S. The debt doesn't get smaller by waiting. But once you see your real date, and how an extra ₹2,000 a month moves it closer, it stops feeling endless. That feeling alone is worth the ₹599.